
When something goes wrong, liability lands in the right place
Risk transfer, proportional to Risk Indicator score, in development.
When something goes wrong, who pays?
Accreditation and Risk Indicator tell you who's fit to connect and how their risk is trending. But when something actually goes wrong: who pays?
Full liability, with no transfer mechanism
Without a liability transfer mechanism, the financial institution holding the customer relationship pays first, in practice, regardless of who's at fault or where formal liability sits. If the responsible party is small, its balance sheet often can't cover the loss anyway; if it's large, recovering anything can mean years in dispute or litigation. Either way, the financial institution can end up bearing the cost and the reputational damage, even when it did everything right.
Being the safest option doesn't get you anything, yet
That's what we're building the mechanism to change. Right now, liability isn't distributed according to who actually introduced the risk, so keeping your own risk profile low doesn't translate into lower cost, easier terms, or a competitive edge with the institutions you connect. Invela Warranty will be that mechanism: proportional accountability that finally pays back the participants who keep their risk low.
Invela Warranty: premiums proportional to risk
Invela Warranty will be the third layer of the network, rewarding the participants who keep their risk low, and shifting economic responsibility to the parties who actually introduce it.
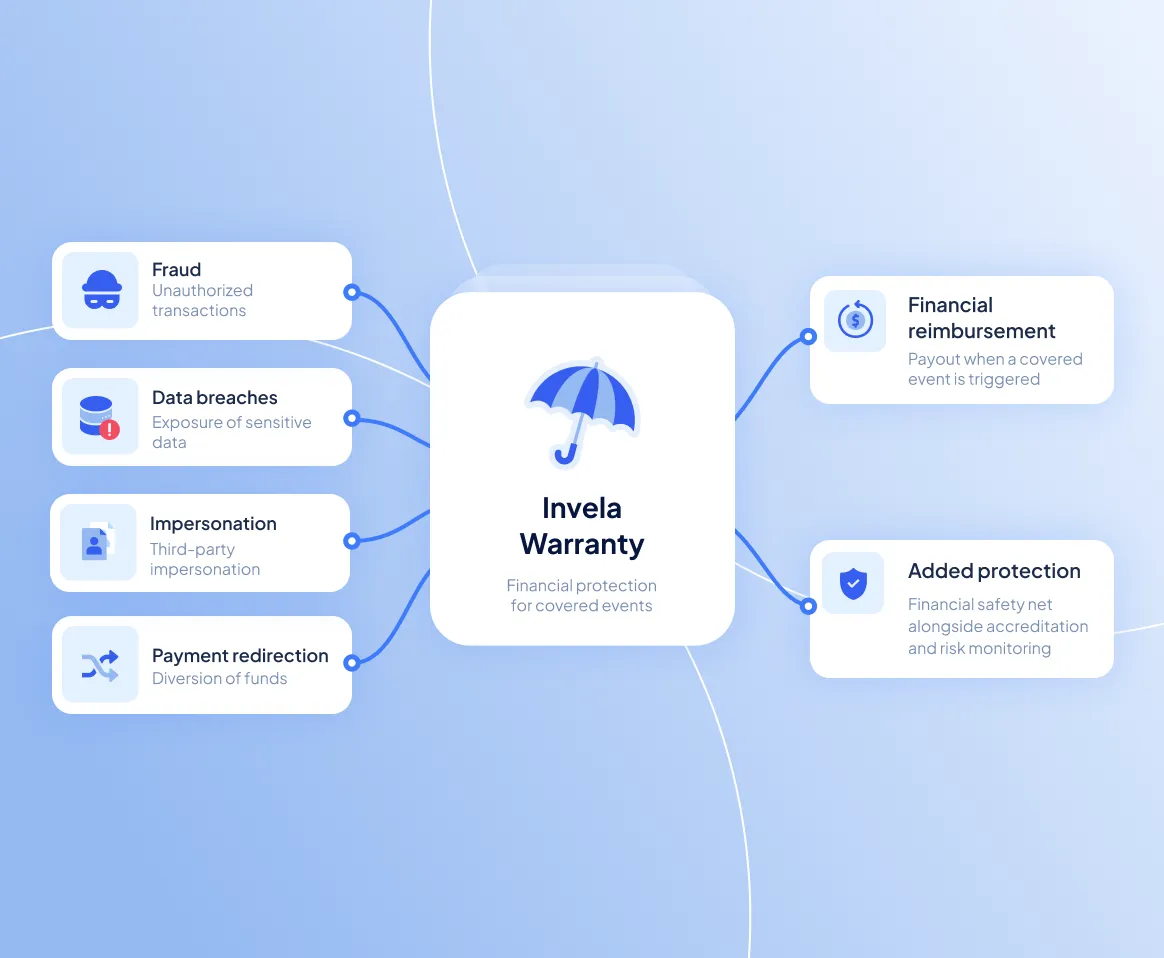
Warranty is designed to help distribute liability proportionally, so participants carry a fairer share tied to the risk they introduce.
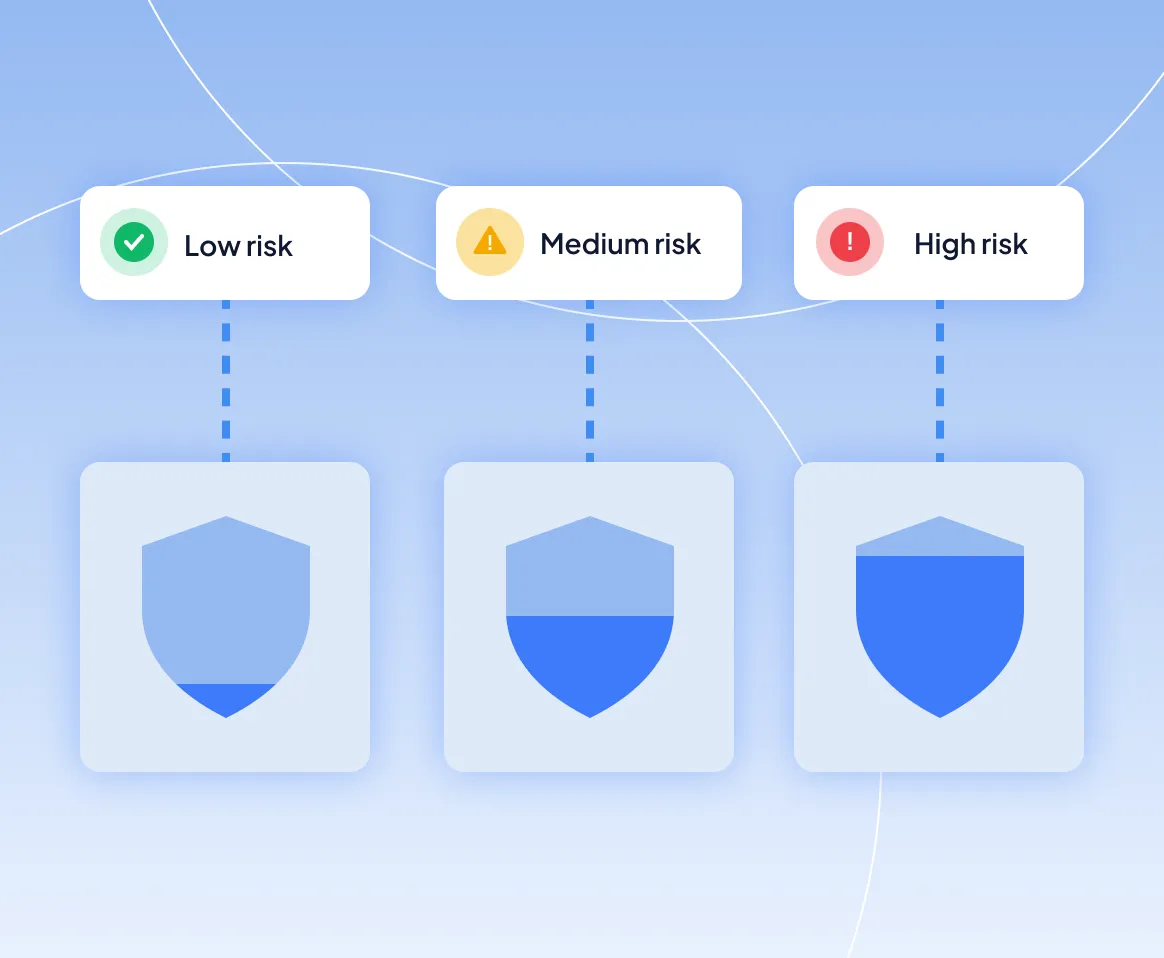
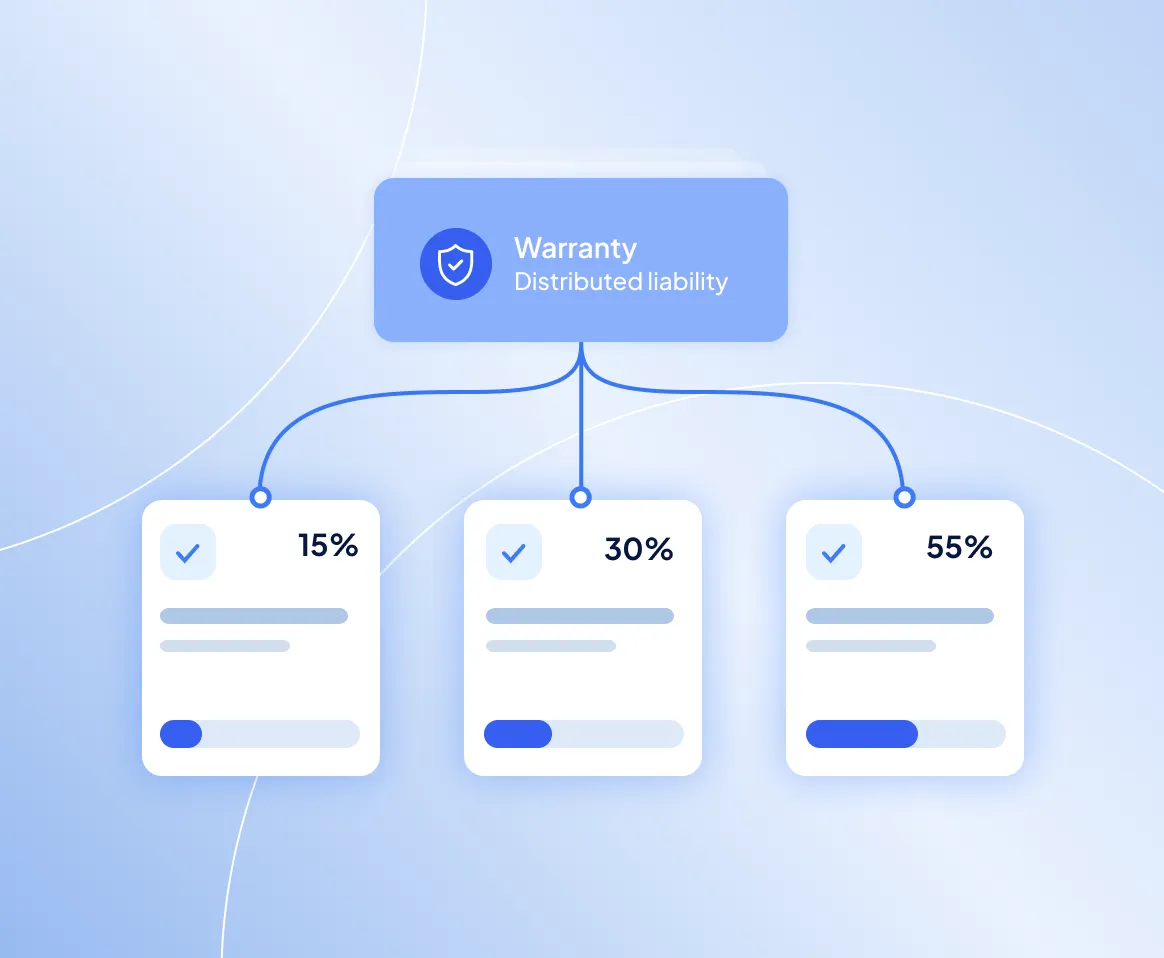
Pricing that reflects real risk, not a flat rate
Accreditation status and Risk Indicator score are expected to inform how Warranty is priced, so it can reflect the risk profile of each participant.
Backed by a carrier, not just a promise
Invela Warranty will be delivered in conjunction with specialist program manager USQRisk and a major insurance carrier, and is intended to provide insurance-backed protection when a covered event occurs, subject to policy terms.
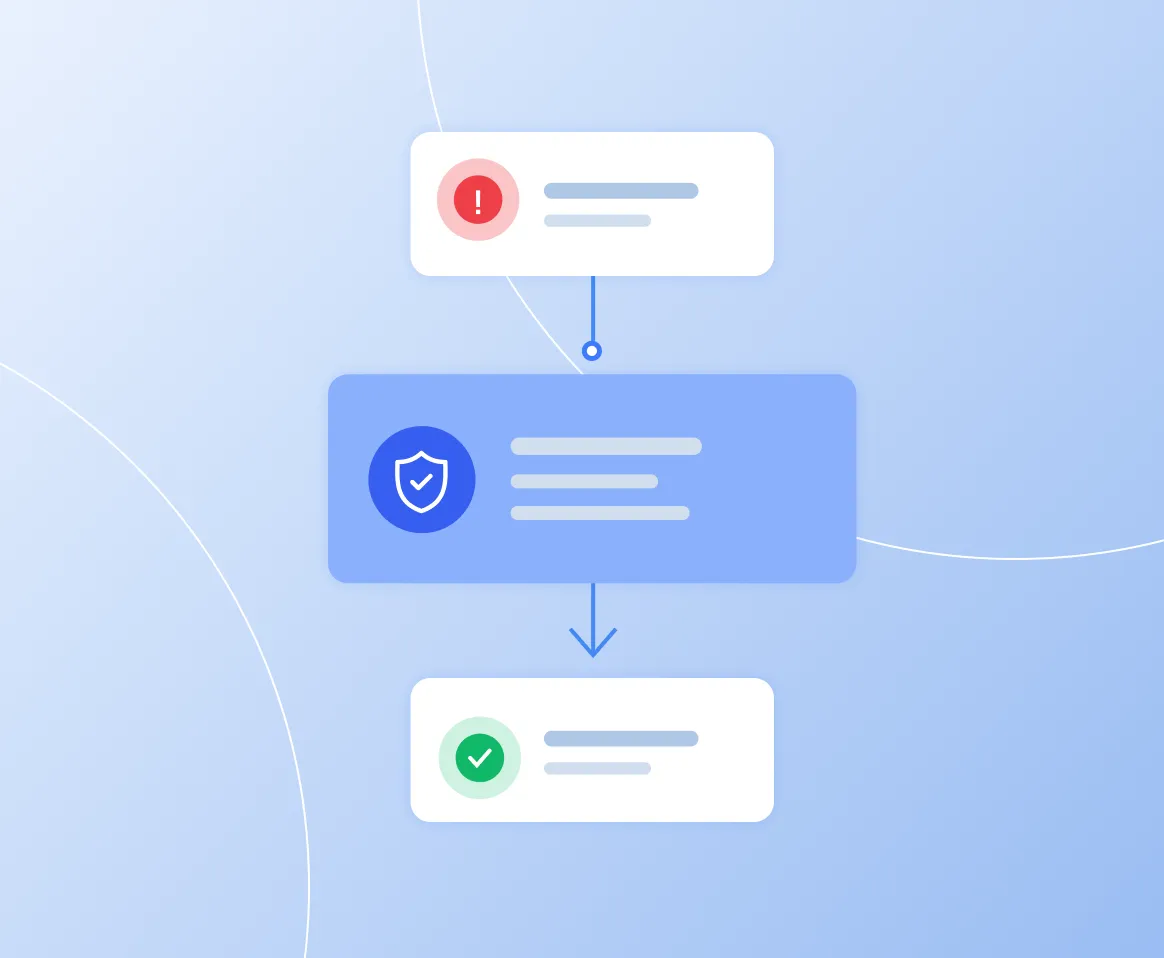
The third layer, not a bolt‑on
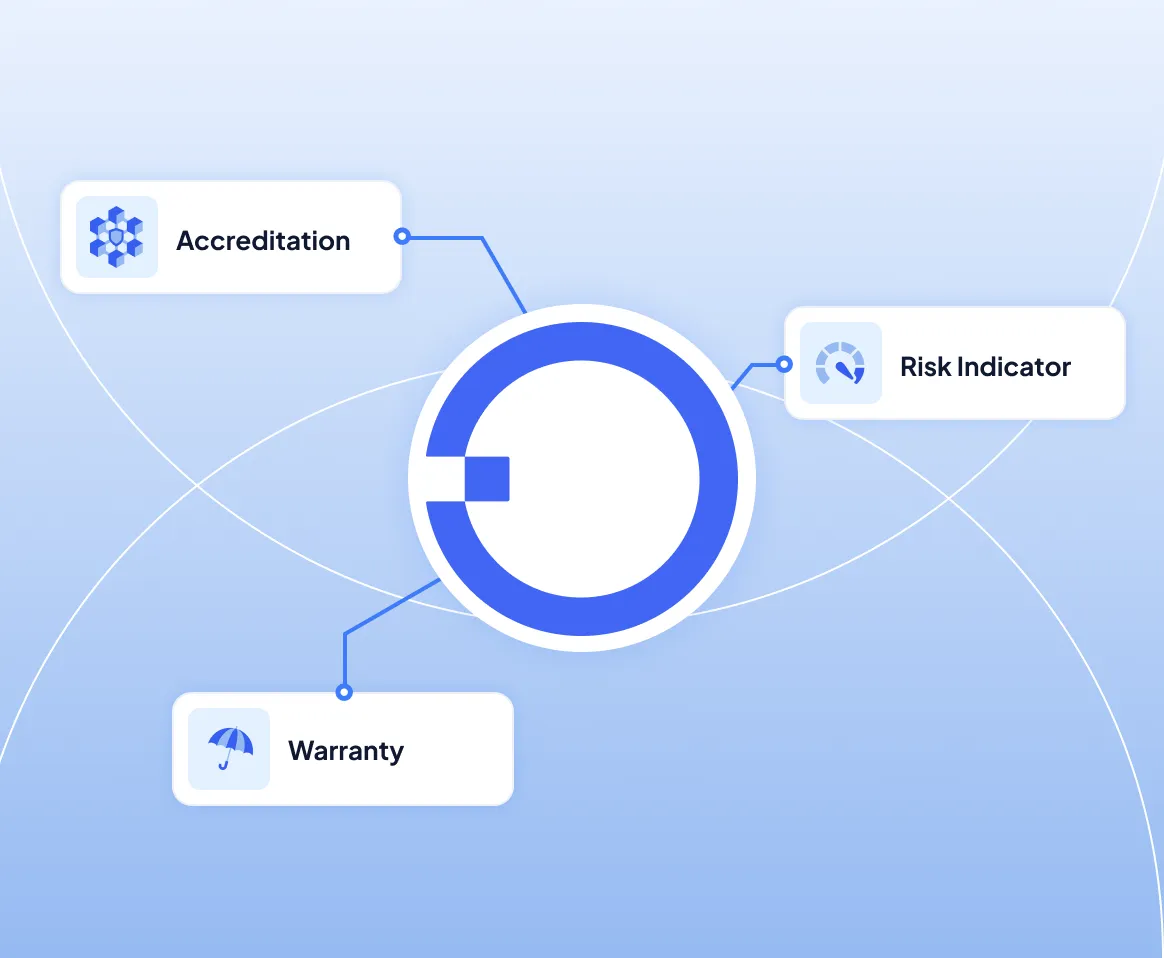
Accreditation establishes trust. Risk Indicator monitors it continuously. Warranty will complete the picture by shifting economic responsibility: one connected network, built from three interlocked solutions.
Covers the risks that actually cause harm
Warranty is initially focused on the financial consequences of data breaches, providing a financial safety net alongside accreditation and risk monitoring. The product is still being specified.
Three steps to risk-based premiums
Warranty will draw directly on the two layers already running in the network.
Your standing sets the baseline
Accreditation status and current Risk Indicator score establish the starting point for how premiums are expected to be calculated for each participant.
Premiums are calculated, not flat‑rated
Use case and data volume are expected to be weighed alongside the risk score when premiums are set. The product is still being specified.
Insurance-backed protection for covered events
If a covered event occurs, the policy terms determine how the loss is addressed.

Open finance risk management insight
Latest industry news and perspectives from the Invela team.

Be first when
Warranty lands
Frequently asked questions
Use Register your interest on the Warranty page. It is a conversation about how Warranty could work for you, with no obligation.
Today, keeping risk low does not translate into lower cost or easier terms. Warranty is designed to change that, with proportional accountability that rewards participants who keep their risk low.
It is designed so that no institution has to fund a failure it did not cause, by tying liability to the participant that introduced the risk.
Without one, the financial institution holding the customer relationship pays first, whoever is at fault. A small responsible party may not be able to cover the loss, and recovering from a large one can take years.
It is initially focused on the financial consequences of data breaches. If a covered event occurs, the policy terms determine how the loss is addressed.
Accreditation status and current Risk Indicator score are expected to set the baseline, with use case and data volume weighed alongside. The product is still being specified, so details may change.
It will be the third layer. Accreditation establishes trust, Risk Indicator monitors it continuously, and Warranty will draw on both to set how risk is priced and carried.
It will be delivered with specialist program manager USQRisk and a major insurance carrier, and is intended to provide insurance-backed protection when a covered event occurs, subject to policy terms.
No. It is in development. You can register your interest on the Warranty page.
A liability management layer that is designed to shift economic responsibility to whoever introduces the risk, with premiums proportional to the participant’s Risk Indicator score. It is in development.
